After the publication of FBK's material on the reporting of Atyrau Airport, in which our editorial team pointed out a recurring error in the calculation of earnings per share and inconsistencies in the notes to the financial statements, FBK sent official enquiries to the company itself and to the Committee for Internal State Audit (CISA). To our surprise, Atyrau Airport directly acknowledged some of the identified problems, demonstrating a willingness to respond openly to the comments, which was clearly not the case with a number of similar companies.
HOW THE AIRPORT EXPLAINED THE ERROR IN THE EARNINGS PER SHARE CALCULATION
In its response to FBK's official enquiry, JSC "Khiuaz Dospanova International Airport" confirmed that in the calculation of basic earnings per share for 2022–2023 a technical error had indeed been made - instead of the profit attributable to holders of ordinary shares, the figure for comprehensive income was used. However, according to the company, this does not change the profit actually earned in the respective periods. 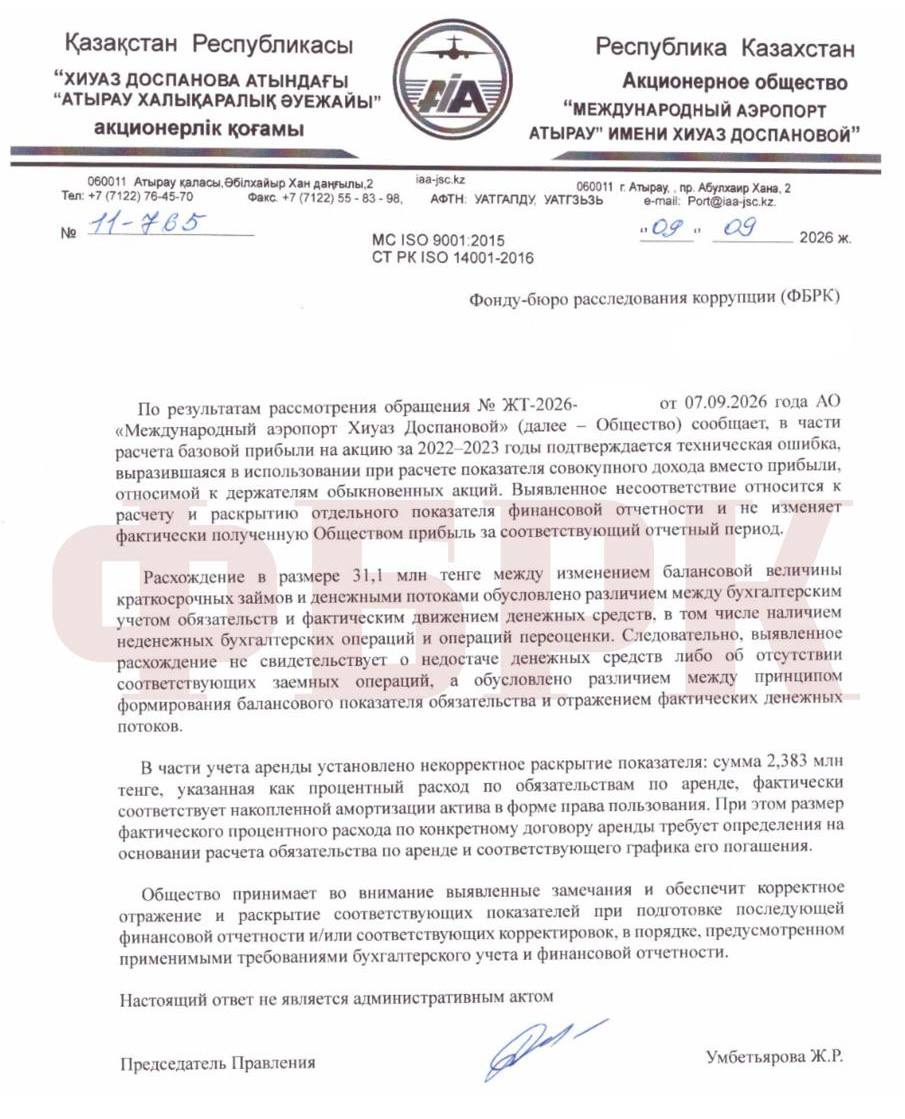
For a state-owned company to openly acknowledge a methodological error in its financial statements is a rare occurrence. It seems all the more unusual against the backdrop of Astana Airport, which initially refused to answer FBK's enquiry, citing the absence of a document confirming the editor-in-chief's authority on the date of the request - a requirement which, as the Ministry of Culture and Information itself later pointed out, simply does not exist in the law.
Against this backdrop, the response of Atyrau Airport is a rare and, in essence, exemplary example of communication and transparency.
WHAT THE AUDIT COMMITTEE SAYS ABOUT THE SAME METHODOLOGY
The CISA, for its part, quoted in detail the methodology of International Accounting Standard (IAS) 33 "Earnings per Share". The numerator is the profit attributable to holders of ordinary shares of the parent organisation, the denominator is the weighted average number of shares outstanding. In essence, the CISA reminded us of the rule which, by the airport's own admission, was breached, but did not directly confirm or deny the existence of a breach in this particular case.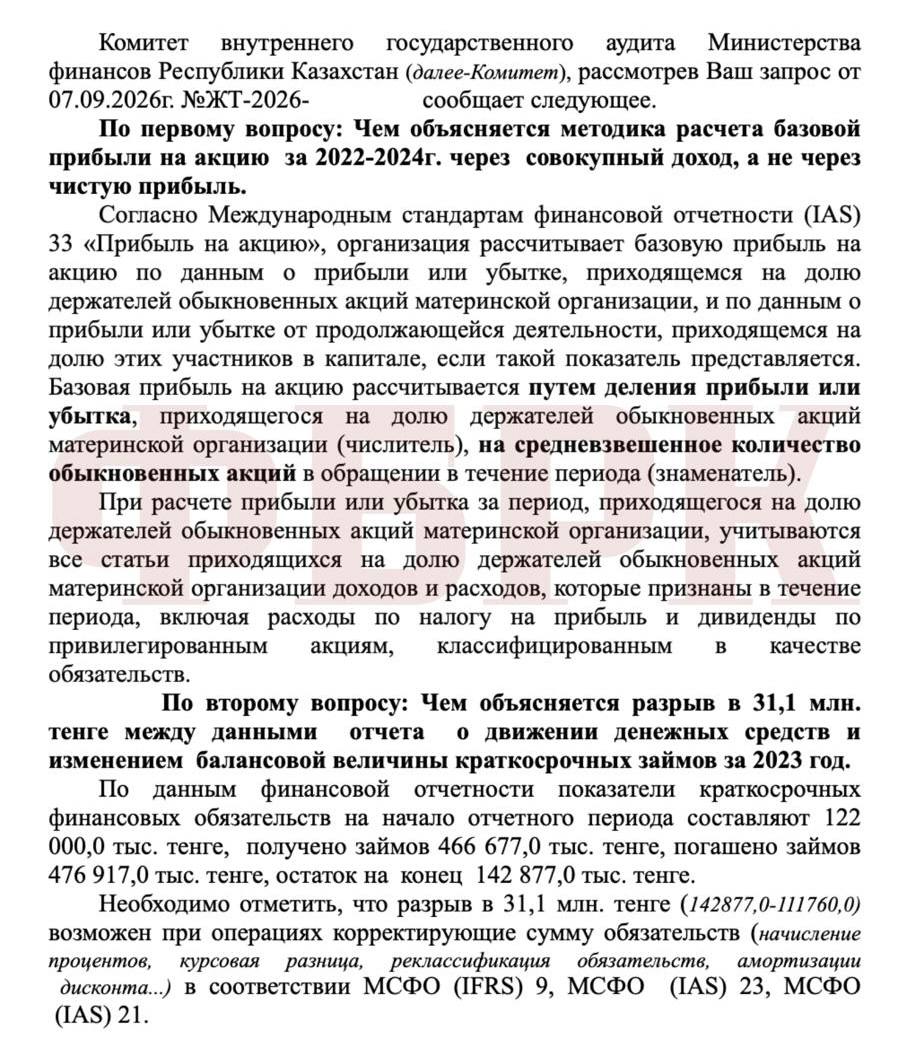
WHERE THE 31.1 MILLION TENGE GAP ON LOANS CAME FROM
Both bodies also responded to the question about the gap between the statement of cash flows and the change in the carrying amount of short-term loans for 2023. The airport explained it by the difference between the accounting treatment of liabilities and the actual movement of money, and stressed that the discrepancy does not indicate either a shortfall in funds or the absence of real borrowing transactions.
The CISA reported that the balance of short-term liabilities at the beginning of 2023 was 122 million tenge, loans received amounted to 466.7 million tenge, and repayments totalled 476.9 million tenge. By simply adding these flows together, the calculated balance at the end of the year would be around 111.8 million tenge, whereas the actual balance in the financial statements is 142.9 million tenge. Hence the gap of 31.1 million tenge, which the committee explained by adjusting entries.
WHAT TURNED OUT TO BE WRONG WITH THE INTEREST EXPENSE ON LEASES
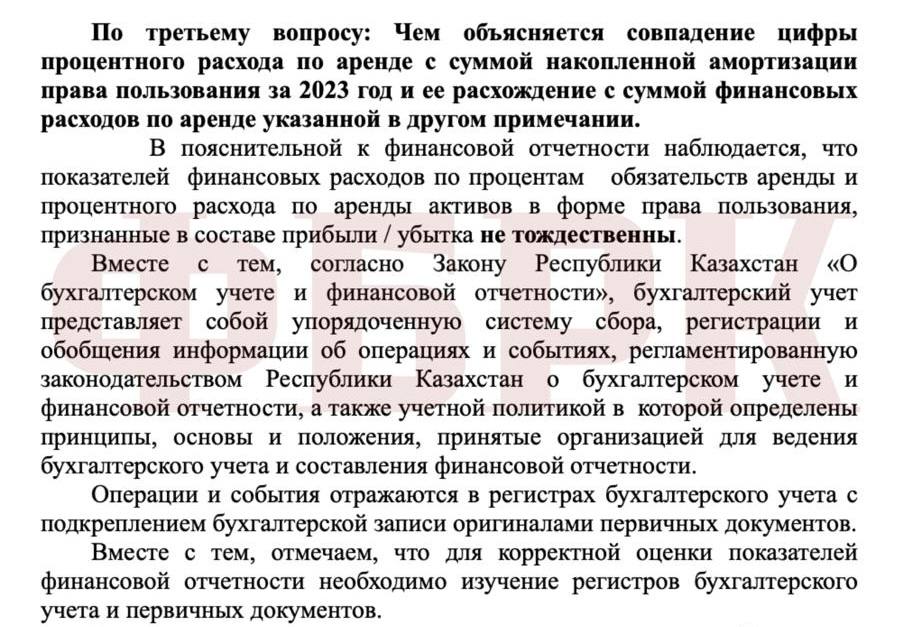
On the third question - why the interest expense on leases in 2023 exactly matched the amount of accumulated depreciation of the right-of-use asset and diverged from the amount of finance costs on leases in another note - the airport also acknowledged an error. The sum of 2.4 million tenge, stated as interest expense on lease liabilities, was in fact depreciation of the right-of-use asset. The real amount of the interest expense, according to the company, requires a separate calculation based on the lease liability and its repayment schedule.
The CISA confirmed only that the figures are "not identical", but did not specify which figure is correct and which is erroneous.
WHAT WILL CHANGE IN THE NEXT FINANCIAL STATEMENTS
The company promises to correct both discrepancies acknowledged by the airport in its next financial statements. Basic earnings per share, which in 2022–2023 was calculated using comprehensive income, is now to be calculated using profit. The interest expense on leases, which previously in effect duplicated the amount of depreciation of the right of use, will be determined separately.